
Blog > What is a Payment Facilitator: Understanding PayFac
What is a Payment Facilitator: Understanding PayFac

What is a PayFac (payment facilitator)?
PayFac, short for payment facilitator, acts as a go-between for merchants and financial institutions to simplify electronic payments.
Instead of individual businesses having to create a merchant account with banks or other merchant account providers, PayFacs have a master merchant account that they use to provide payment services to numerous sub-merchants. This simplifies the onboarding process for businesses looking to accept credit card payments, granting them faster access to payment systems.
A PayFac takes the burden of managing the complex aspects of payment processing, such as PCI compliance standards, risk management, and handling various payment methods like credit and debit cards, online payments, and mobile payments.
The payment facilitator model is often a good fit for software companies and other service providers that want to incorporate payment acceptance into their offerings to enhance the user experience.
Some key features of PayFac services include merchant onboarding, payment processing services, risk and compliance management, and offering multiple payment methods.
With this setup, businesses can concentrate on their core products or services, leaving the complex yet crucial task of payment facilitation to a specialized provider.
How does a PayFac work?
Since PayFacs act as middlemen between businesses and banks during the payment process, it’s important to understand their role behind the scenes.
Instead of individually setting up a merchant account with banks or other financial institutions, businesses can quickly onboard through PayFac.
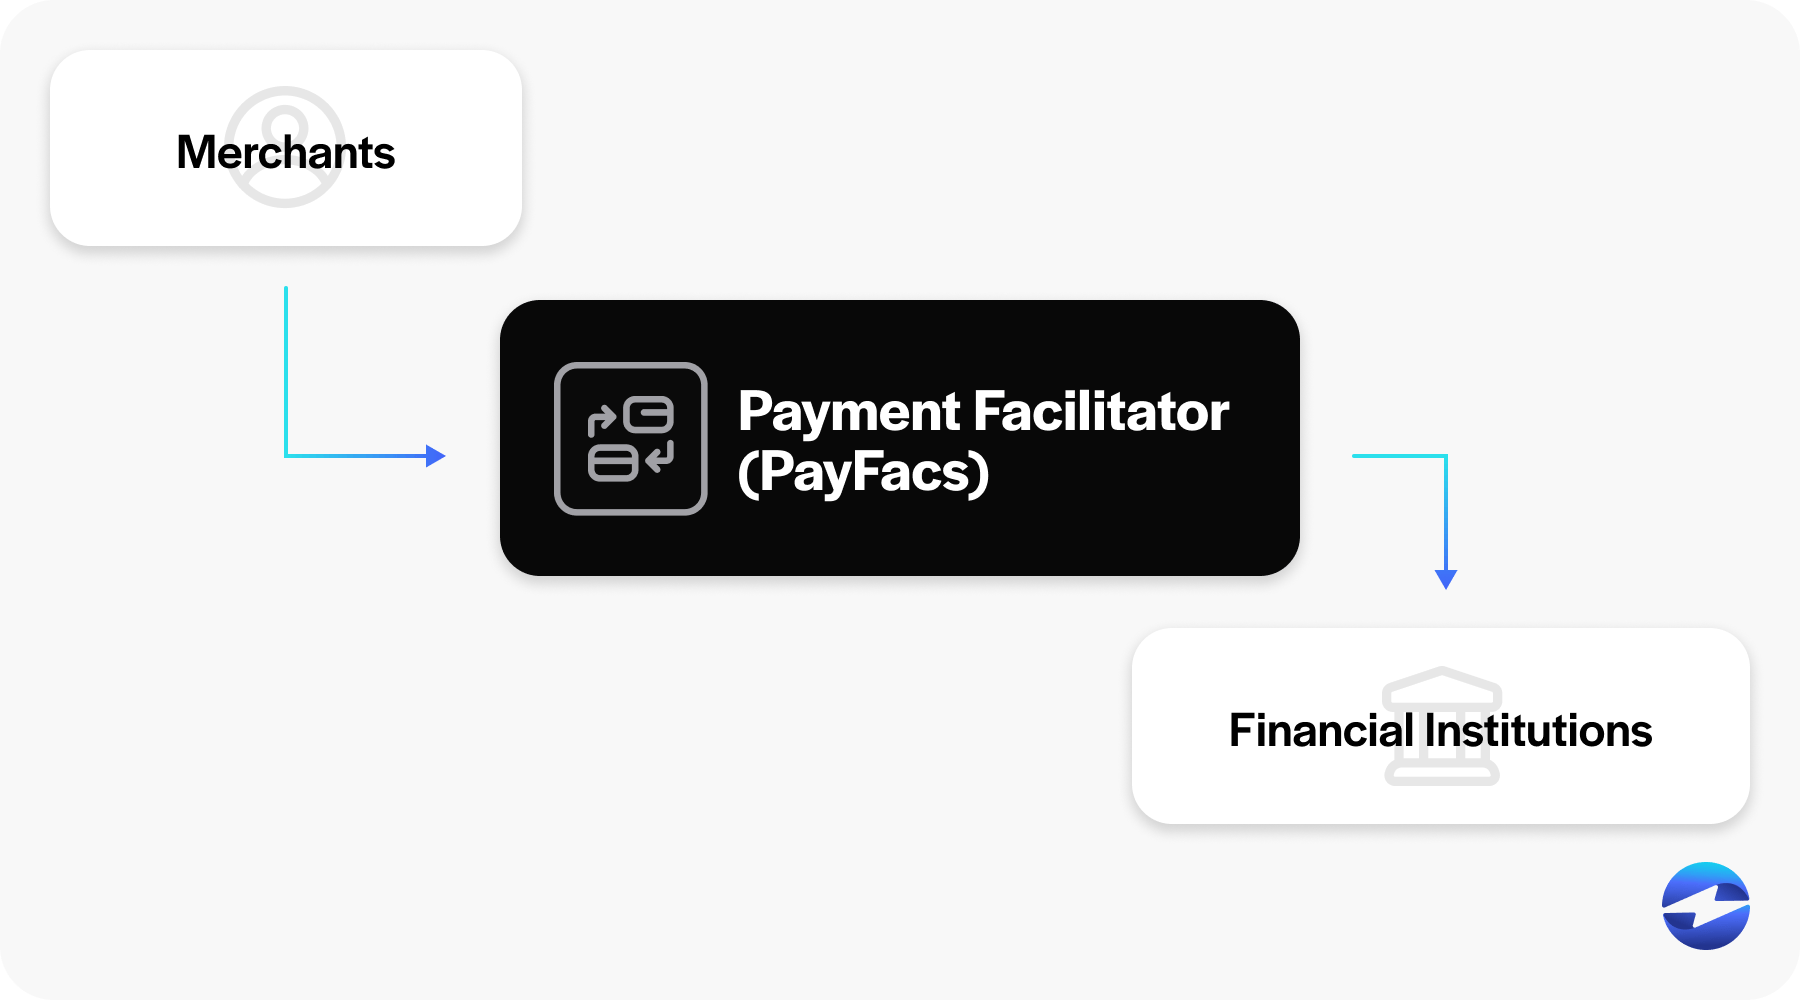
Here’s how it works:
- Sign-up: Businesses can sign up with a PayFac provider who becomes the master merchant.
- Simplified onboarding: The PayFac handles the underwriting and due diligence by evaluating and verifying businesses for eligibility, usually with quick approval turnaround times.
Through payment facilitation, businesses gain access to a payment ecosystem without the individual burden of managing their payment processing operations.
Why are they important?
PayFacs have become crucial cogs in the modern payments landscape for several reasons.
Firstly, PayFacs significantly lower the barrier to entry for small to mid-size businesses when it comes to accepting digital payments by offering a more straightforward onboarding process.
PayFac providers also help their clients navigate payment compliance with regulations like PCI compliance, which governs how credit card data is handled. Since failure to comply with such regulations can result in substantial fines and legal issues, these facilitators alleviate merchants’ stress.
Lastly, PayFacs provide speedy and reliable payment processes to enhance customer satisfaction and loyalty, enabling businesses to grow and maintain a competitive edge.
What are the main differences between PayFac solutions, payment processors, and ISOs?
Understanding the roles and differences between a PayFac, payment processor, and an Independent Sales Organizations (ISO) is essential for businesses looking to select a payment solution that best suits their needs.
Each offers a distinct business model with various degrees of service, control, and responsibility in the payment acceptance process.
PayFac vs Payment Processor
Payment facilitators and payment processors offer essential services in processing online and electronic payments, yet they function differently in the payment value chain.
- Engagement model:
- PayFacs act as master merchants, signing up businesses (sub-merchants) under their umbrella and facilitating a simplified merchant onboarding process.
- Payment processors handle the technical aspect of processing transactions but don’t manage merchant accounts directly.
- Control and flexibility:
- PayFacs provide greater control over the payment experience and customer journey, including branding and user interface.
- Payment processors offer standardized services that are more rigid and less customizable.
- Risk and compliance:
- PayFacs assume responsibility for underwriting and compliance risks as they onboard and manage sub-merchant accounts.
- Payment processors transfer risk management and PCI compliance to the merchants, who must manage these obligations directly.
- Support and services:
- PayFacs typically offer a more comprehensive suite of services, including billing, customer support, and handling disputes.
- Payment processors focus on processing payments and often require merchants to handle frontline customer service and dispute resolution.
- Cost structure:
- PayFacs may offer competitive pricing models due to their aggregated volume and often cater to niche markets.
- Payment processors generally charge per-transaction fees and other associated costs, which may vary based on individual merchant volume
PayFacs vs ISOs
While PayFacs and ISOs are both involved in merchant services, they serve businesses differently.
- Merchant relations:
- PayFacs directly manage the relationship with their sub-merchants and offer a more seamless payment facilitation service.
- ISOs act as intermediaries that work with merchant acquirers to set up individual merchant accounts.
- Service integration:
- Payment facilitators are often integrated into software platforms, providing a cohesive user experience for businesses and their customers.
- ISOs provide payment services that may integrate with various external systems.
- Simplicity and efficiency:
- PayFacs enhance the payment acceptance process, making it simpler and more efficient for small businesses to start accepting payments.
- ISOs can offer personalized service but may require more extensive documentation and longer approval times for merchant accounts.
- Merchant portfolio:
- PayFacs manage many small to mid-sized businesses through a single merchant account structure.
- ISOs manage individual merchant accounts, which can provide businesses with more autonomy but also more responsibility.
- Financial opportunities:
- PayFacs earn a portion of the transaction revenue by charging a percentage fee, which allows them to benefit from the efficiencies gained as transaction volumes increase.
- ISOs earn income through account setup, equipment, and transaction fees that are often tailored to each merchant’s processing volume.
Overall, PayFacs offer integrated, streamlined services ideal for software platforms and SMEs looking for fast payment acceptance with minimal hassle. Whereas payment processors focus strictly on transaction handling, and ISOs focus on individual account services that suit businesses seeking more direct relationships with merchant service providers.
Reshaping the payments ecosystem with EBizCharge
EBizCharge’s payment solution takes the traditional merchant account model a step further with native accounting and ERP integrations that embed payment processing directly into the software your team already uses, so every transaction posts to your books automatically without a separate reconciliation step.